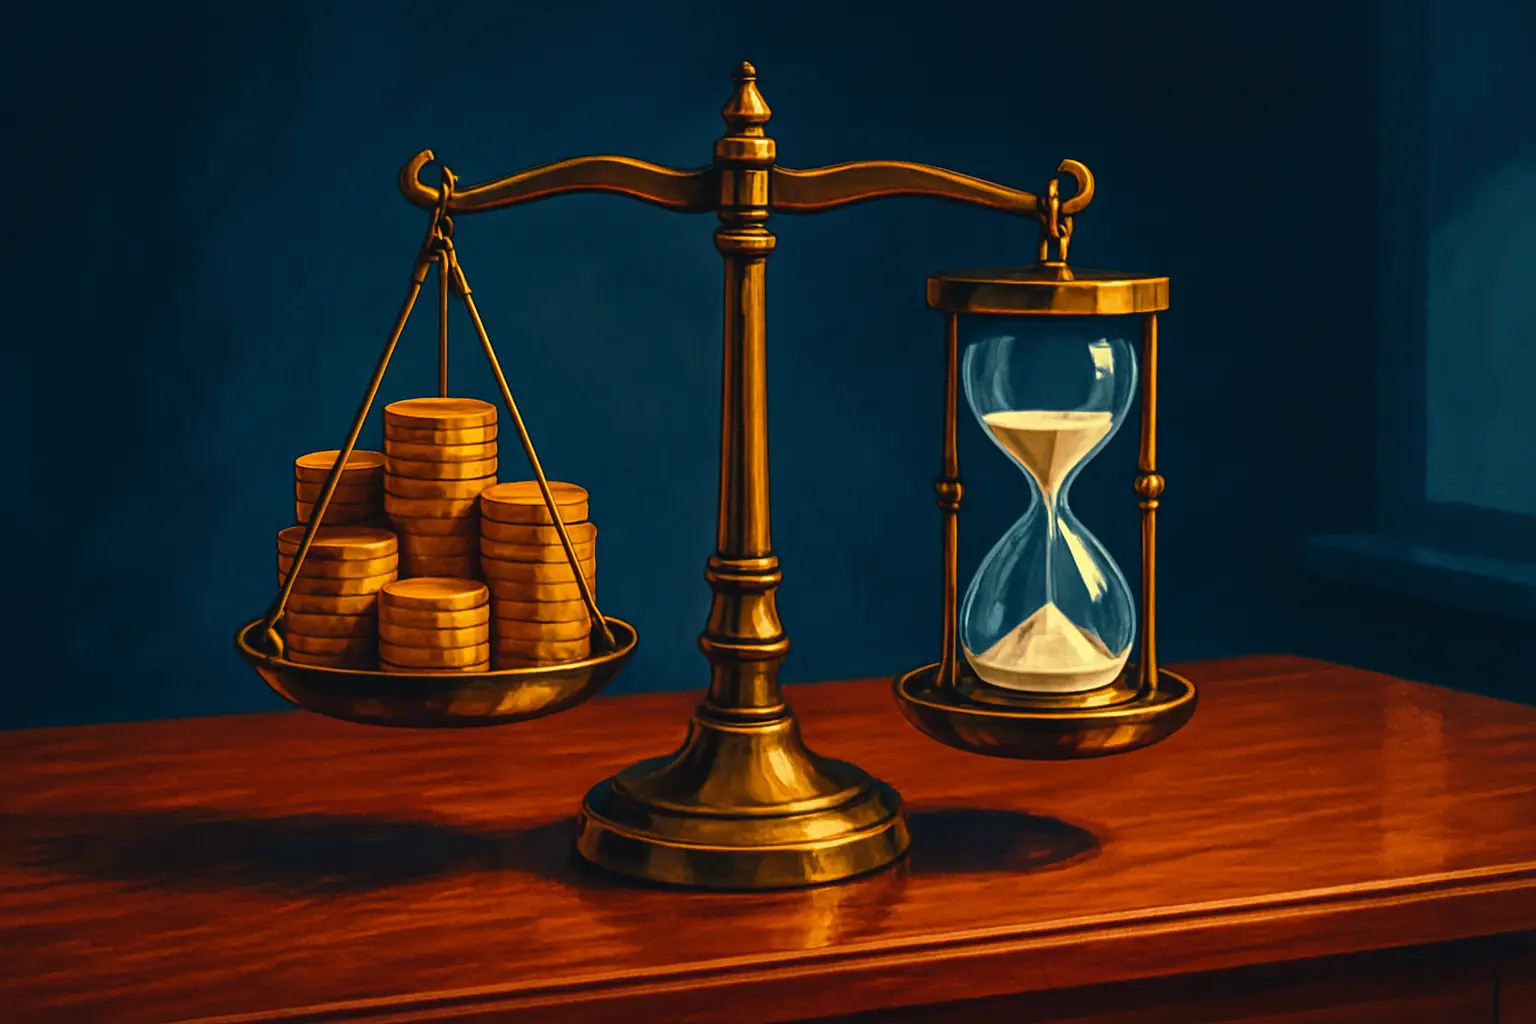
The Illusion of the Risk-Free Return: What Every Investor Gets Wrong
Few financial myths are as stubbornly persistent — or as quietly ruinous — as the belief that somewhere, just beyond one's current knowledge, there exists an investment that is both perfectly safe and meaningfully profitable. Financial advisers call it the search for the free lunch. Behavioural economists have a more clinical term: the illusion of the risk-free return. Whatever you call it, the phenomenon is responsible for an extraordinary proportion of the wealth destruction that ordinary people bring upon themselves, not through recklessness, but through a misplaced and entirely human desire for certainty.
The relationship between risk and return is one of the closest things finance has to a genuine law. Capital markets are, in aggregate, ruthlessly efficient at pricing uncertainty: if an asset reliably offered high returns with negligible risk, capital would flood in until the return eroded to something commensurate with its safety. This is not theory dressed up as wisdom; it is the observable consequence of millions of competing actors pursuing self-interest across interconnected markets. The corollary, which far fewer people internalise, is that whenever an investment appears to defy this logic — offering outsized gains with apparent security — the hidden risk has simply been displaced, deferred, or obscured. It has not been eliminated.
This displacement takes many forms, each capable of fooling even financially literate people. Structured products with complex payoff schedules routinely bury tail-risk — the possibility of catastrophic loss — in fine print and probabilistic language that discourages scrutiny. Property, beloved by a generation who watched it appreciate relentlessly, carries liquidity risk that only becomes visible when you urgently need to sell into a falling market. Cash savings, seemingly the safest choice of all, erode silently under inflation, transferring purchasing power from the saver to the economy with a stealth that headline interest rates do little to offset. In each case, the risk is real; only its visibility differs.